 FolkKeeper
“Half of Mom’s check was gone in December.”
5 min read · Composite story · Names and details changed
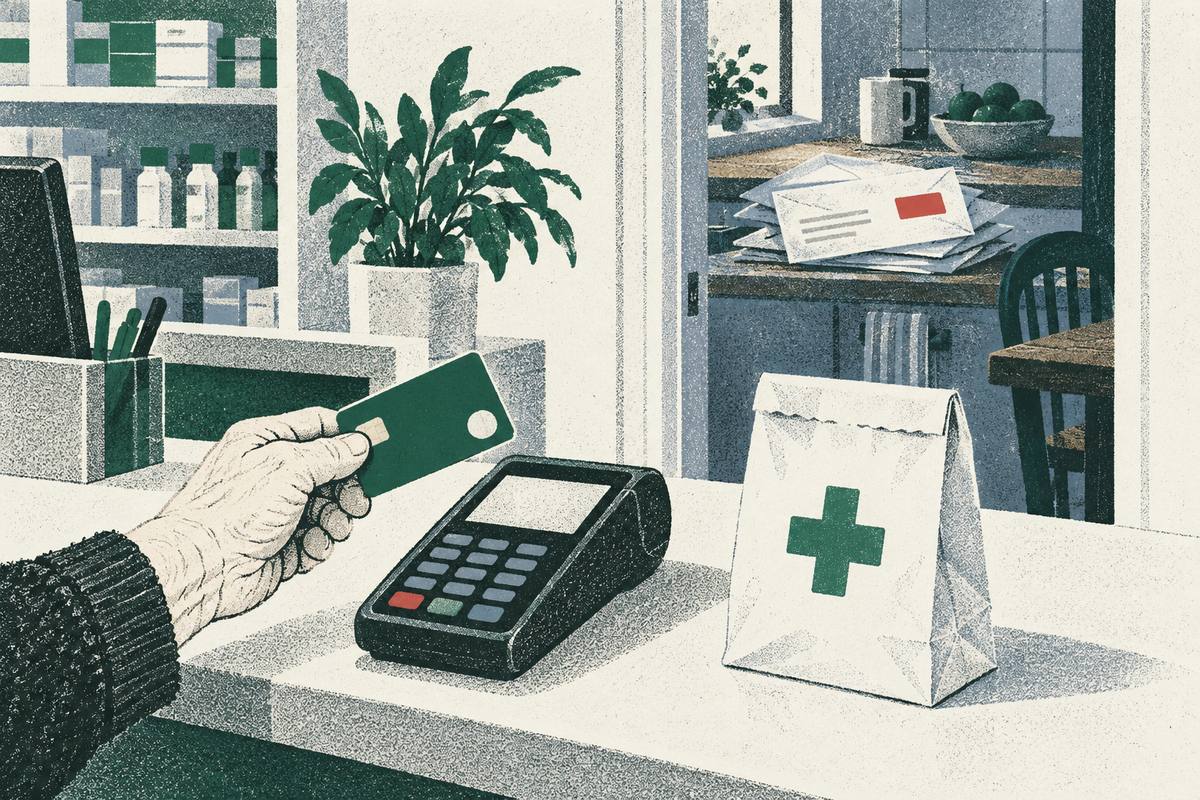
Linda found out on December 3rd, at the pharmacy. Her mother’s card was declined. The Social Security deposit had come in at $1,214 instead of $2,428.
The letter had arrived in October. It said SSA had overpaid her mother $9,880 after recalculating her survivor benefit, and that it would hold back half of each check until the money was repaid. It was in a pile of mail on the kitchen counter, under a seed catalog and two bank statements.
“Nobody opened it. It looked like every other envelope from them.”
Her mother, Ruth, is 79. She has lived in the same rented apartment for eleven years, and her budget has no slack in it: rent, the electric bill, a car insurance payment, groceries, and two prescriptions that her Part D plan does not fully cover. Half a check covered the rent and almost nothing else.
Linda sat down at her mother’s table that night with the letter, a highlighter and a calculator. The first thing she looked for was the date printed at the top: October 10. SSA treats a notice as received five days after that date, so October 15. From there, the letter gave 30 days to ask for a waiver or an appeal and keep SSA from collecting while it decided. That window had closed in mid-November. The 60 days to ask SSA to reconsider were still open until December 14. She had 11 days.
Then she read the reason. As far as she could tell, it was right. SSA had paid her mother more than it should have after a change in how her survivor benefit was figured, and the months on the letter matched the bank statements. An appeal says SSA got the facts wrong. It hadn’t.
That left two other doors. A waiver asks SSA to forgive the money when the person was not at fault and repaying would be a hardship. A lower rate keeps the debt but spreads it out. Linda thought her mother had done nothing wrong, but proving that would take time and paperwork, and in the meantime the next check would be cut in half again. She decided to do the fast thing first: ask for a lower rate now, and look at a waiver once the rent was safe. A waiver can be requested at any time.
The lower-rate form is SSA-634, Request for Change in Overpayment Recovery Rate. Most of it is a household budget. Linda spent a Saturday with her mother’s statements and filled it in with real numbers, not guesses: rent of $1,350, about $160 for electric and phone, $96 for car insurance, $380 for groceries, $140 in pharmacy copays, $120 for her Medicare supplement. After all of that, about $180 a month was left from a full check. She proposed $150 a month.
She took the form to the Social Security office in person on Monday and asked for a dated receipt. That afternoon she called 1-800-772-1213 as well, asked the agent to note the request on her mother’s record, and wrote down the date, the time and the agent’s ID on the back of the receipt.
What she did
- 1Read the dates. The 30 days to stop the withholding had passed. The 60 days to appeal had not. She had 11 days left, and she wrote both dates on the calendar.
- 2Asked for a lower rate. The amount was right, so she filed SSA-634 with her mother’s rent, pharmacy and utility bills, and proposed $150 a month.
- 3Called and wrote it down. She called 1-800-772-1213, asked the agent to note the request, and logged the date and the agent’s ID. She kept copies of every page.
What happened
Five weeks later, SSA wrote back agreeing to $150 a month. The check at the end of January was back to $2,278. The rest of the debt is still being repaid, slowly, without a missed rent. Linda has the waiver form in a folder and plans to file it in the spring, with a short timeline of what her mother reported and when. There is no deadline for that.
What she would do differently: open every envelope from SSA the week it comes, and put the date on the calendar before anything else. A lower rate is not guaranteed, and SSA can ask for more proof or offer a different number. A clear budget made the answer easy to give.
Stories are composites of cases families commonly face. Names and details are changed. Dates and rules follow SSA's published guidance; check them against your own letter. Not legal advice; FolkKeeper is not a law firm and is not affiliated with SSA.